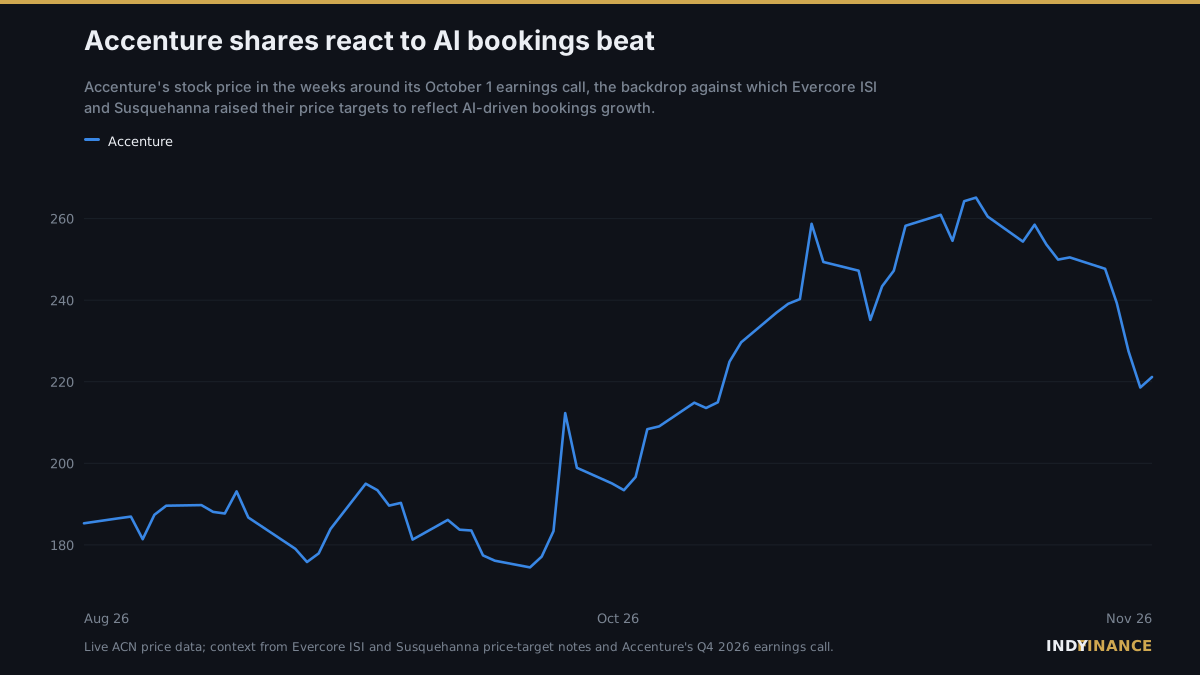
Accenture reported fiscal fourth-quarter results and held its earnings call on October 1, prompting a wave of analyst upgrades. Evercore ISI raised its price target to $250, pointing to AI growth as the main driver. Susquehanna also lifted its target, citing strong bookings in the same release.
The moves suggest Wall Street sees Accenture's consulting and AI-implementation work translating into bigger contract wins, a signal other IT-services firms will be watched against. Bookings growth is the metric analysts use to judge future revenue, since consulting deals often take quarters to convert into billed work.
What remains unclear is how much of the bookings strength is new AI-related spending versus existing clients shifting budget from other technology categories. The next data point will be Accenture's first-quarter fiscal 2027 bookings disclosure.