Regional Banks Post Double-Digit Loan Growth Despite Rate Pressure
Four separate community and regional bank earnings calls this quarter showed accelerating loan books even as lenders warn on credit costs elsewhere in the sector.
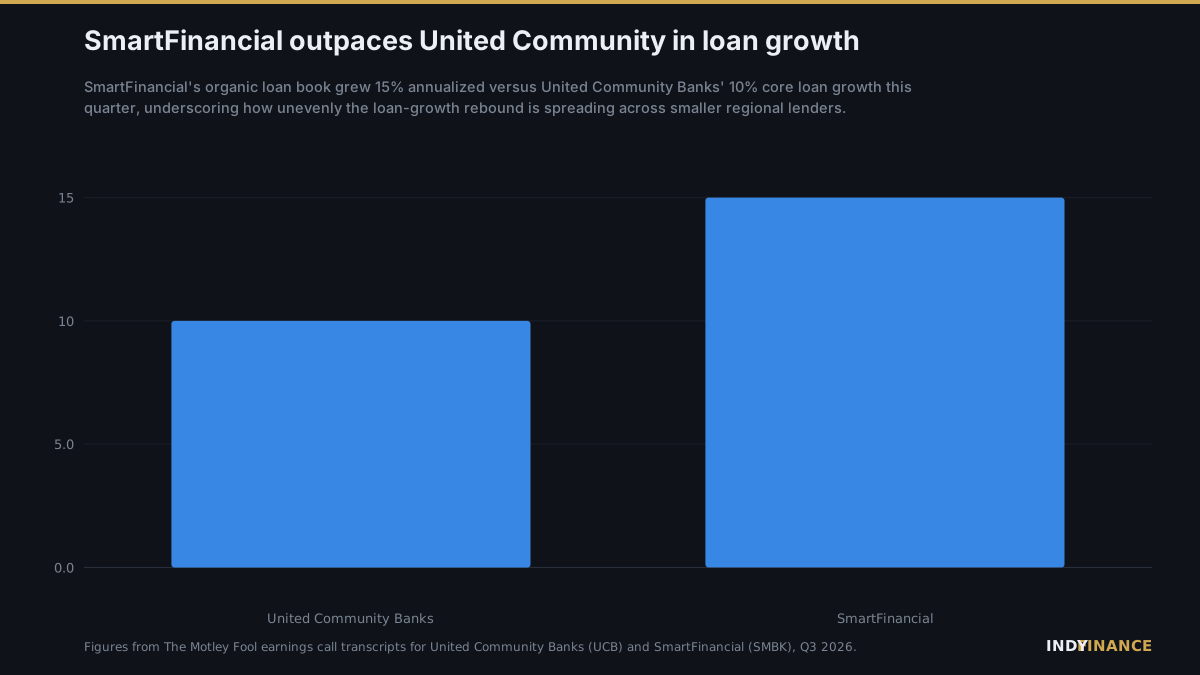
United Community Banks reported operating EPS of $0.77 on 10% annualized core loan growth, while SmartFinancial posted 15% annualized organic loan growth, pointing to a stronger-than-expected quarter for smaller regional lenders.
SmartFinancial outpaces United Community in loan growth
SmartFinancial's organic loan book grew 15% annualized versus United Community Banks' 10% core loan growth this quarter, underscoring how unevenly the loan-growth rebound is spreading across smaller regional lenders.
Figures from The Motley Fool earnings call transcripts for United Community Banks (UCB) and SmartFinancial (SMBK), Q3 2026.
Use this chart
Free to embed with attribution:
<figure><a href="https://www.indy.finance/news/regional-banks-post-double-digit-loan-growth-despite-rate-pressure"><img src="https://www.indy.finance/news/regional-banks-post-double-digit-loan-growth-despite-rate-pressure/graphic.svg" alt="SmartFinancial outpaces United Community in loan growth" width="1200" height="675"></a><figcaption>SmartFinancial outpaces United Community in loan growth — <a href="https://www.indy.finance/news/regional-banks-post-double-digit-loan-growth-despite-rate-pressure">Indy Finance</a></figcaption></figure>If credit costs cited by Home Bancorp show up broadly in the next round of regional bank earnings and loan growth rates like SmartFinancial's 15% slow materially, the resilience narrative would not hold.
- Investing.com — All NewsHome Bancorp Q3 2026 slides: record income offset by credit costsExternal ↗
- Seeking Alpha — All ArticlesKeyCorp (KEY) Q3 2026 Earnings Call TranscriptExternal ↗
- The Motley FoolSmartFinancial (SMBK) Q3 2026 Earnings Call TranscriptExternal ↗
- The Motley FoolWintrust: 3 Key Takeaways for Long-Term InvestorsExternal ↗
- External ↗
Produced automatically by the INDY NEWS Desk from the public wire sources cited above, and checked against them before publication. Market commentary, not investment advice.