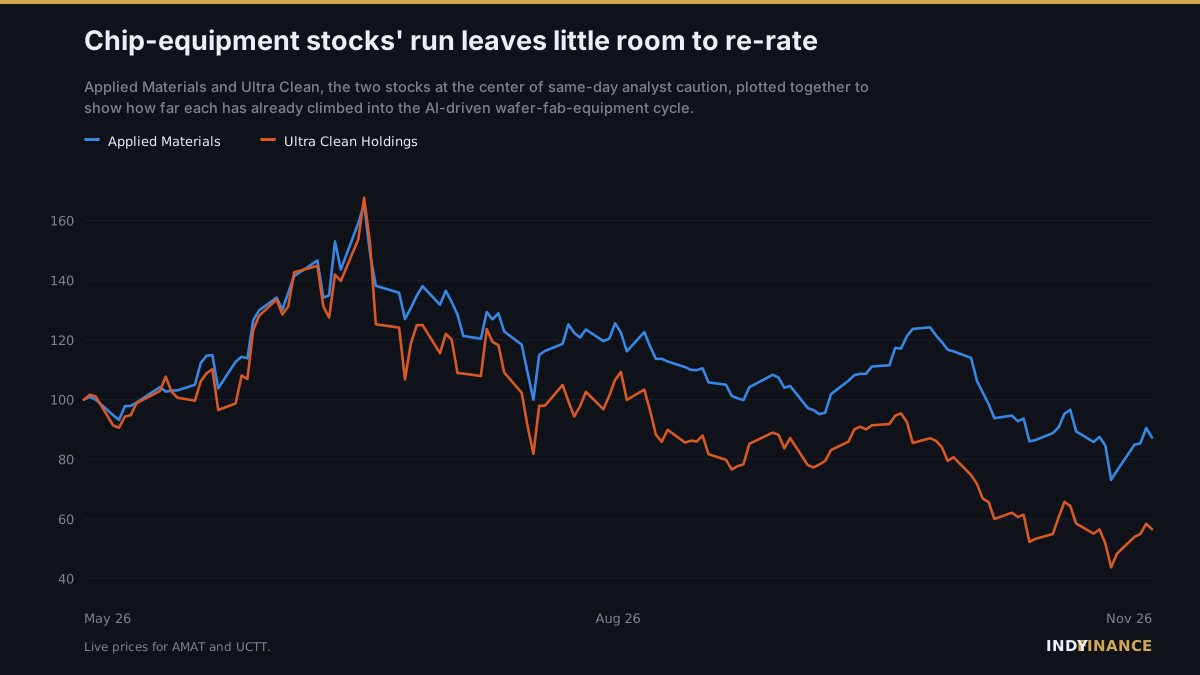
Applied Materials' Q4 2026 earnings call framed the company's growth problem as physical, not demand-driven: clean-room capacity, the sealed, particle-controlled space needed to build chip-making tools, is now what gates how fast the company can scale shipments. That is normally a bullish signal — it implies orders are outrunning supply, not demand.
But the stock-specific reaction cut the other way. Summit Insights downgraded Applied Materials the same day, citing valuation concerns rather than any weakening in the business itself. Separately, Barclays initiated coverage of equipment supplier Ultra Clean at Equalweight, even while naming wafer-fab-equipment growth as its reason for starting coverage.
The pattern across both calls is the same: analysts are not disputing that chip-equipment demand is strong, tied to the broader AI buildout. They are disputing how much of that strength is already priced into the stocks. A capacity-gated grower that gets downgraded on valuation, and a supplier initiated at a hold-equivalent rating despite a bullish sector thesis, both say the same thing — the growth story is intact, but the re-rating room for these shares may already be used up.
What is unresolved is whether Applied Materials can convert its capacity constraint into pricing power, which would justify the valuation Summit Insights flagged as stretched. The December-quarter guidance will be the next test of that.