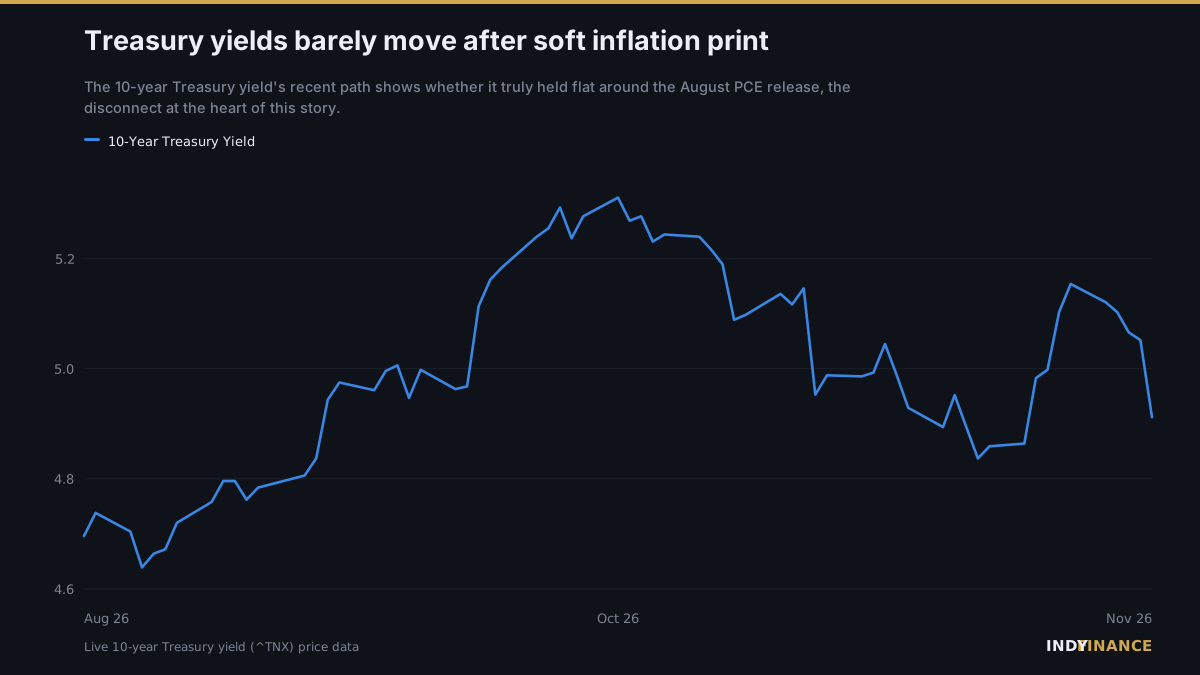
The core Personal Consumption Expenditures price index, the Federal Reserve's preferred inflation gauge, rose 0.2% in August, according to a Motley Fool report, less than economists had expected. Normally a softer-than-expected inflation print would be read as a reason for bond yields to ease, since it reduces pressure on the Fed to keep rates high. That didn't happen this time: Treasury yields stayed roughly where they were.
Separately, Goldman Sachs pushed back its forecast for the next Federal Reserve rate hike to December, according to Investing.com. The combination — soft inflation data paired with a delayed hike call and unmoved yields — suggests bond markets are pricing in factors beyond the latest inflation print, such as the government's borrowing needs or broader growth expectations.
What's unresolved is exactly why yields aren't responding to the softer inflation data the way they typically would. That disconnect is the detail worth watching heading into the Fed's next policy meeting.